
28 min read
On 26 August 2024 at 5:11 in the morning, an earthquake in Portugal was felt in the Greater Lisbon area, in Setúbal and as far as Porto. According to the Portuguese weather and seismology institute IPMA, the quake had a magnitude of 5.3, and the centre lay about 60 kilometres off Sines in the Atlantic. Nobody was injured and there was no major damage.
A good occasion to check what your own home insurance pays in an earthquake in Portugal. Under the terms of Fidelidade and Generali, earthquake insurance in Portugal is an add-on: the policy pays only if you have expressly agreed earthquake cover. Under those terms it is not part of the basic cover, nor of the fire insurance that is compulsory for apartments in a condomínio (a building divided into separately owned units with shared common parts). So check your own policy.
This guide is based on the policy terms of Fidelidade (Fidelidade Casa Mais, September 2026) and Generali (Multirrisco Casa, July 2025), the leaflet of Portugal’s civil protection authority ANEPC and the Portuguese Insurance Contract Act. The sources are linked where they are used. If you only want to know what to do during an earthquake, go straight to What to do in the event of an earthquake in Portugal.
- Portugal is an earthquake region. The last major quake on the mainland, on 28 February 1969, had a moment magnitude of 8.0 according to IPMA; it was felt most strongly in the Algarve.
- Earthquake insurance is not compulsory in Portugal today. According to an analysis by the insurance supervisor ASF, only about one in five dwellings had earthquake cover at the end of 2022.
- With Fidelidade and Generali, earthquake cover is an add-on module (Fenómenos Sísmicos). You are insured only if it appears in your condições particulares (the schedule of your policy).
- A fire started by an earthquake is excluded from the compulsory fire cover of both sets of terms. It is insured there only through the earthquake module.
- The excess for earthquakes is set in the condições particulares: with Generali as a percentage, with Fidelidade as a percentage where the insurer’s liability is only partial, and a franquia (deductible) may be added. Check whether the percentage applies to the loss or to the sum insured.
- With Fidelidade and Generali, all damage within 72 hours of the first damage counts as one claim. Aftershocks in that period do not trigger a second excess under these terms.
- On 28 April 2026 the government announced a catastrophe fund and compulsory insurance for residential buildings. As far as we could establish, no law on this had been published by October 2026.
- In an earthquake in Portugal the rule is: Baixar, Proteger, Aguardar, that is, drop to your knees, protect your head, wait until the ground is still. Emergency number 112.
How high is the earthquake risk in Portugal?
Portugal lies close to the boundary between the Eurasian and the African plate and is therefore one of the earthquake regions of Europe. Noticeable quakes are rare and strong ones rarer still, but they do happen, and the damage from a single large quake can be very high. The Lisbon earthquake of 1 November 1755 is still part of the national memory: together with the tsunami and fires that followed, it destroyed large parts of the city.
The last major quake: 28 February 1969
IPMA describes the quake of 28 February 1969 as the last major earthquake on the Portuguese mainland. Its centre lay in the Atlantic off the south-west coast of Portugal (36.01° N, 10.57° W), and its moment magnitude was later determined as 8.0. The strongest shaking (intensity VIII) was observed in the Algarve, and intensity VI in Lisbon. In Portugal 13 people died, two of them directly from the quake (IPMA, 45 anos do sismo de 28 de fevereiro de 1969).
A noticeable quake of recent years: 26 August 2024
On 26 August 2024 the ground shook with a magnitude of 5.3, about 60 kilometres west of Sines. It was felt in the Lisbon area, in Setúbal and as far as Porto, and calls came from the Alentejo to Coimbra; the civil protection authority reported no injuries and no major damage (RTP, 26 August 2024, citing IPMA). That is the typical situation: a quake that wakes people from their sleep but leaves no damage. It is the rare large quakes that become expensive.
Is earthquake insurance in Portugal part of home insurance?
In the two sets of policy terms we examined, home insurance pays for an earthquake only if earthquake cover has been expressly agreed; it is an add-on module there. Fidelidade lists Fenómenos Sísmicos (seismic phenomena) among the coberturas facultativas, the optional covers that the contract includes only “quando contratadas”, in Fidelidade’s own English translation “when taken out” (Fidelidade Casa Mais, Condições Gerais MR011, September 2026, no. 6.1). Fidelidade’s terms are bilingual, but its English text is a non-binding translation; only the Portuguese wording is legally binding. Generali treats earthquake as a special condition (Condição Especial) of its own that applies only if it is provided for in the condições particulares (Generali Multirrisco Casa, Condições Gerais Mod. 465.031, July 2025).
An analysis by the Portuguese insurance supervisor ASF shows how widespread the gap is: according to it, only 19 to 20 per cent of all dwellings had earthquake cover at the end of 2022, and about 79 per cent of the estimated rebuild cost of the housing stock would have been uninsured in an earthquake (ECO, 23 April 2024, citing the ASF financial stability report).
Where to find it in your policy
Whether you are insured is shown in the condições particulares, the part of the policy with your personal details, sums and chosen modules. Look there for “Fenómenos Sísmicos” or a similar name such as “Sismos”. If the module is not in the list, the earthquake peril is not covered; a fire after the earthquake is then expressly excluded, and whether individual consequential losses are paid under other modules depends on their own terms. Also check whether the cover applies to the building, the contents or both; Generali expressly distinguishes between the sum for the building and the sum for the contents when it comes to the excess.
The name of the Portuguese home insurance invites the assumption that it covers everything. In fact, with Fidelidade and Generali only a basic scope is fixed; earthquake, storm and flood are among the modules you add yourself. Read the list in your condições particulares, not the product name.
What earthquake cover pays for
With Fidelidade and Generali, earthquake cover pays for damage to the insured property that arises directly from earthquakes, tremors, volcanic eruptions, seaquakes and tidal waves (maremotos) and underground fire, and in addition for fires that these events cause. Fidelidade words it as: “danos sofridos pelos bens seguros em consequência da ação direta de tremores de terra, terramotos, erupções vulcânicas, maremotos e fogo subterrâneo e ainda de incêndio resultante destes fenómenos”. In Fidelidade’s own English version: “damage suffered by the insured property as a result of the direct action of tremors, earthquakes, volcanic eruptions, tidal waves and underground fires and fires resulting from these phenomena”. Generali uses almost the same wording. Payment is up to the sum set in the condições particulares, less the excess.
The 72-hour rule
Both sets of terms combine all damage within 72 hours into one claim. At Fidelidade this covers all damage to the insured property in the 72 hours after the first damage, at Generali all events within 72 hours after the first damage. For you this means: an aftershock the next day is not a new claim, and the excess applies only once. The clauses regulate only this 72-hour window; whether a later aftershock counts as a new claim is decided by the insurer according to the circumstances.
Tremores de terraQuake
Damage to insured property caused by the direct action of the quake falls under the module in both sets of terms, up to the agreed sum, less the excess and subject to the exclusions in the next section.
MaremotoTsunami
The maremoto, that is, seaquake and tidal wave, appears in the list of insured events in both sets of terms.
IncêndioFire after quake
A fire caused by the quake is insured with Fidelidade and Generali only through the earthquake module, not through the fire cover.
The exclusion is stated word for word in the compulsory fire cover: Fidelidade excludes “Incêndio decorrente de fenómenos sísmicos, tremores de terra, terramotos e erupções vulcânicas, maremotos ou fogo subterrâneo” (no. 5.1 f), in its own English version “Fire resulting from seismic phenomena, tremors, earthquakes, volcanic eruptions, tidal waves, or underground fires”. Generali has the same wording (Cláusula 3.ª n.º 1 f). In the other covers, Fidelidade applies the same exclusion, expressly without prejudice to the rights under the earthquake module (no. 5.2.2 e).
What is not insured even with earthquake cover
Even with earthquake cover agreed, Fidelidade and Generali exclude buildings that were already damaged and buildings made predominantly of non-resistant material. The two sets of terms word this differently, and Fidelidade also ties it to the building regulations in force when the building was built.
| Point | Fidelidade Casa Mais (09/2026) | Generali Multirrisco Casa (07/2025) |
|---|---|---|
| Earthquake cover | add-on module among the coberturas facultativas | special condition (Condição Especial) of its own, only if agreed |
| Fire caused by an earthquake | only with the earthquake module | only with the earthquake module |
| One claim | all damage within 72 hours of the first damage | all events within 72 hours of the first damage |
| Excess | where the insurer’s liability is agreed only in part: a percentage share in the loss, plus a franquia (deductible), both in the condições particulares | percentage according to the condições particulares, described in the earthquake clause as a share of the loss; the general rule mentions a possible share of the sum insured |
| Construction and building regulations | excluded if not designed to the regulations in force when built and not predominantly built of resistant materials, or if these materials make up less than 50% | excluded through the general terms: buildings of “reconhecida fragilidade” (recognised fragility) such as timber or plastic sheets, buildings with less than 50% resistant material, buildings in an obviously dilapidated condition; also buildings that have not been legalised, where the damage results from that |
| Previously damaged building | excluded if stability and safety were already impaired | excluded if stability and safety were already impaired |
| Wholly or partly abandoned building earmarked for demolition | excluded | no express exclusion in the earthquake clause; buildings to be demolished are valued only at their tax value (valor matricial), and dilapidated buildings fall under Cláusula 3.ª n.º 3 a |
The table compares two sets of policy terms, not the market. Other insurers handle individual points differently, and in both cases the percentages are not in the general terms but in your policy.
Older buildings: construction and building regulations
Fidelidade excludes damage to constructions “que não tenham sido dimensionadas de acordo com a regulamentação vigente à data da construção e cuja estrutura, paredes exteriores e cobertura não sejam maioritariamente construídas com materiais resistentes”, in its own English version “which have not been built in accordance with the dimensions set out in the regulations in force at the time they were built and which have a structure, external walls and roof which are not predominantly built with resistant materials”. In the Portuguese wording, both conditions are joined by “e” (and). As resistant materials the terms name iron, steel, stone, reinforced concrete, masonry and ceramic roof tiles, and as non-resistant, among others, timber and plastic. A separate item (b) also excludes constructions in which the resistant materials do not make up at least 50 per cent.
Generali has no such exclusion in the earthquake clause itself but refers there to the general terms. Their Cláusula 3.ª n.º 3 excludes, for the optional covers, damage to constructions “de reconhecida fragilidade (tais como de madeira ou placas de plástico)” (of recognised fragility, such as timber or plastic sheets), to constructions in which the resistant materials do not make up at least 50 per cent, and to buildings in an obviously dilapidated condition. The clause contains no link to the building regulations in force when the building was built.
For an old country house in the Algarve or a town house in Lisbon, this is a question to settle before a loss, not after. Ask the insurer to confirm in writing that your house has been accepted for the earthquake module, and keep the year of construction, the building permit and records of renovations.
Consequential damage under other covers
Some other modules exclude damage during an earthquake and in the 72 hours after the last tremor. At Fidelidade this applies, among others, to landslip (Aluimento de Terras), there with the proviso that the condições particulares do not provide otherwise, and also to aerials, solar panels and falling fixed furniture and light fittings. At Generali the exclusion applies to the module for falling fixed furniture and light fittings (Queda acidental de mobiliário fixo). If you have no earthquake module, do not count on another module to absorb earthquake damage.
In an earthquake, it is not the name of your policy that decides but a single line in the condições particulares: whether Fenómenos Sísmicos appears there.
Excess for earthquakes: what the percentage applies to
The excess for earthquakes with Fidelidade and Generali is set in the condições particulares, usually as a percentage, and it makes a big difference whether it applies to the loss or to the sum insured. For the case where the insurer’s liability is agreed only in part, Fidelidade describes a share in the loss “com base na percentagem a seu cargo” (based on the percentage borne by the insured) plus a franquia, which Fidelidade’s English text calls a deductible. In its earthquake clause, Generali mentions a percentage that always stays with the insured as “parte do sinistro garantido”, that is, as a share of the loss; the general valuation rule, by contrast, says that a “quota-parte do capital seguro”, a share of the sum insured, may stay with the insured. Which basis applies in your contract is stated in the condições particulares; have it explained to you in writing.
Suppose a house is insured for 300,000 EUR for the building. An earthquake causes cracks and a collapsed chimney, and the repair costs 40,000 EUR.
| Contract design | Deduction | Payout |
|---|---|---|
| 5% of the loss | 2,000 EUR | 38,000 EUR |
| 5% of the sum insured | 15,000 EUR | 25,000 EUR |
| 5% of the sum insured, loss 12,000 EUR | 15,000 EUR, your share 12,000 EUR | 0 EUR |
The percentages are assumed and only show the calculation. An additional franquia is not taken into account. If the percentage applies to the sum insured, a loss of several thousand euros can stay entirely with you; the insurance then mainly covers the large loss.
A sum insured that is too low aggravates the problem, because with underinsurance the insurer pays only proportionately; at Generali, this reduction applies only once the difference exceeds 15 per cent. What counts is the rebuild cost, not the purchase price. How to work it out is shown in our guide Calculating rebuild costs in Portugal.
Apartment in a condomínio: compulsory fire insurance and earthquakes
For an apartment in a condomínio in Portugal, the law makes only fire insurance of the building compulsory, not earthquake insurance. The Código Civil provides: “É obrigatório o seguro contra o risco de incêndio do edifício, quer quanto às fracções autónomas, quer relativamente às partes comuns.” (fire insurance of the building is compulsory, both for the individual units and for the common parts) (Artigo 1429.º n.º 1 Código Civil). Whether a policy for the whole building includes earthquakes depends on whether the condomínio has added the module.
In a multi-unit building, rebuilding can also fail because of a single owner without cover. Portugal’s civil protection authority ANEPC says so in its leaflet on earthquakes (as of November 2018), which it produced in cooperation with the Portuguese Insurance Association APS: “E se vive num prédio, certifique-se que todos os condóminos têm essa cobertura. Lembre-se que, basta um não ter, para poder inviabilizar a reconstrução de todo o edifício.” In other words, if you live in an apartment building, make sure that all owners have the cover, because even one owner without insurance can prevent the whole building from being rebuilt (ANEPC, Sismos. Prepare-se e proteja-se).
So ask the building administrator which policy the condomínio has taken out and whether it includes earthquakes. You insure your own apartment, your contents and your liability through your own house insurance in Portugal.
Catastrophe fund and compulsory insurance: what has been announced
There is no compulsory insurance against earthquakes in Portugal today. A catastrophe fund and compulsory insurance for residential buildings have been announced, and their scope is still open. On 28 April 2026 the government announced, as part of the PTRR (Portugal Transformação, Recuperação e Resiliência), a fund for natural and earthquake disasters and compulsory insurance for residential buildings and business infrastructure, with a support mechanism for low-income households (Government of Portugal, announcement of 28 April 2026). In May 2026 the Minister of Economy expected the law to come into force in 2027 (ECO, 18 May 2026).
As far as we could establish, it had not been determined by October 2026 which risks the obligation will cover, which minimum sums will apply or when it will take effect. We explain the announcement and what it means for owners in our article Home insurance in Portugal is becoming compulsory. For earthquake cover this means: if you have none today, you are not insured today. Waiting for the law does not protect you from an earthquake in the meantime.
What to do in the event of an earthquake in Portugal
In an earthquake in Portugal, the civil protection authority ANEPC recommends three actions: “Baixar, Proteger, Aguardar”, that is, drop to your knees so that you do not fall, protect your head, neck and eyes with your arms and hands, and wait until the ground stops shaking. ANEPC’s emergency plan is divided into before, during and after; all the recommendations that follow come from its leaflet.
Prepare
House and family
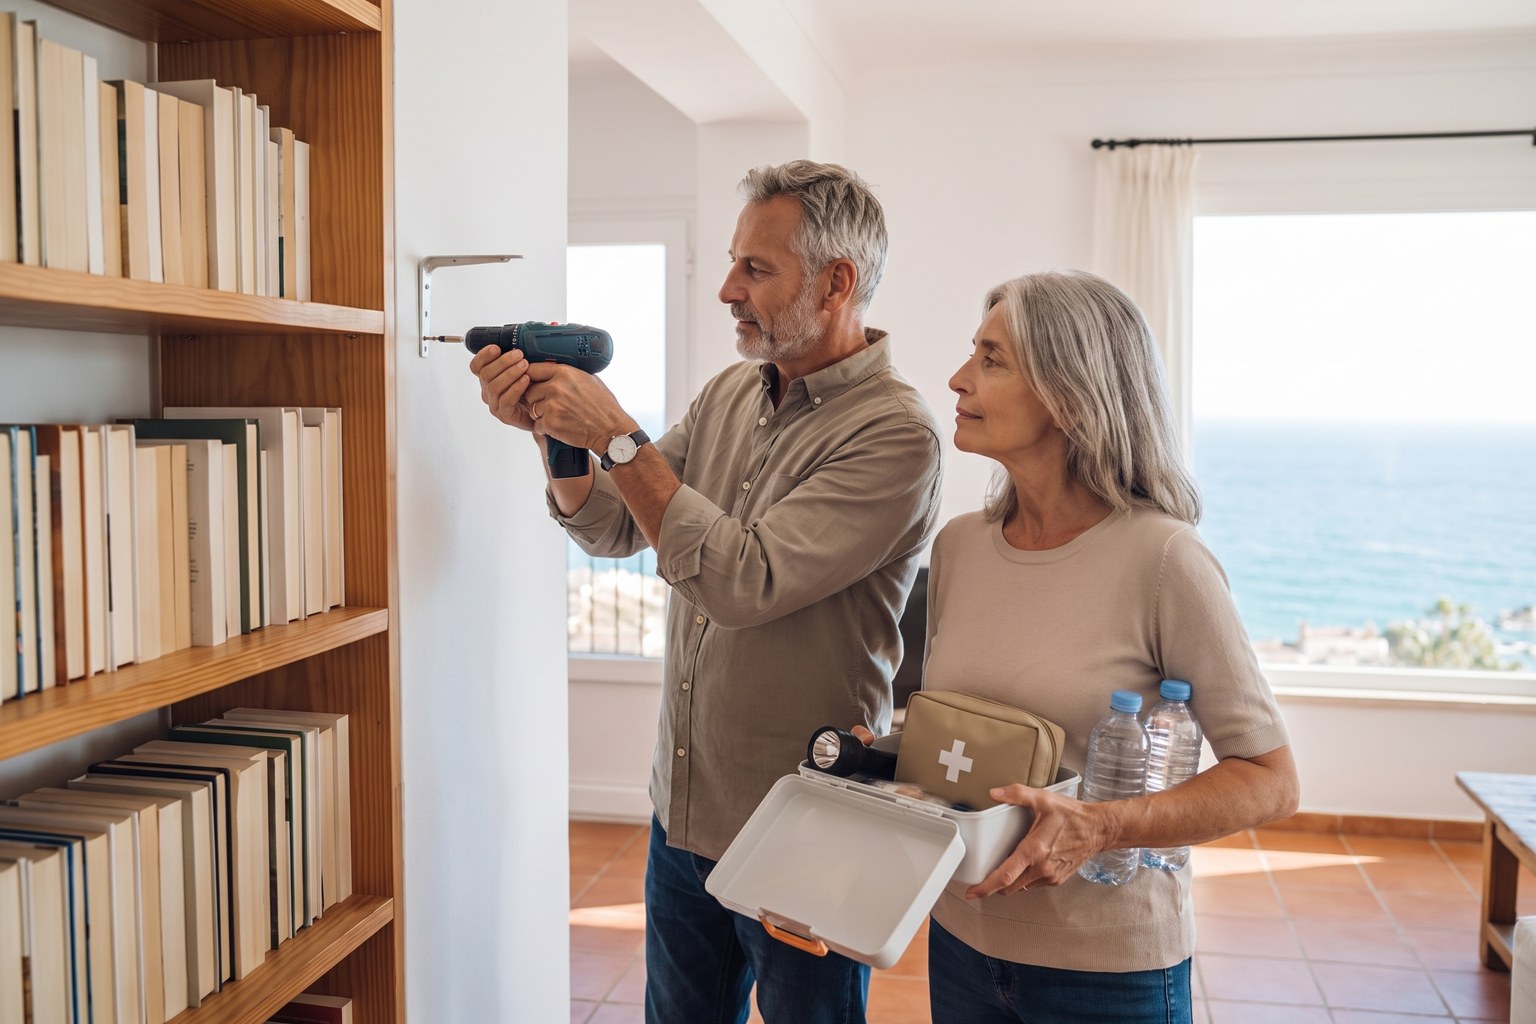
Fix shelves and heavy furniture to the wall and put heavy objects at the bottom. Decide on safe places: interior doorways, corners of load-bearing walls, under tables and beds. Know the dangerous places: next to windows, mirrors, lamps and furniture that can fall over, lifts and exits to the street. Keep water and tinned food for two to three days and show everyone how to turn off electricity, water and gas.
Baixar, Proteger, Aguardar
Take cover where you are
Indoors, do not rush to the exit; stairs and doors quickly fill with debris. Take cover at a beam or pillar, in a corner of the room or under a sturdy table or bed. Never use the lift. Outdoors, keep away from buildings and poles; in a car, stop and stay seated.
Make safe, 112
Aftershocks, tsunami, emergency call
Expect aftershocks and possibly a tsunami. Turn off water and gas, switch off the electricity, use no naked flames. Leave a badly damaged house; as soon as you can, go to an open place, preferably high up and away from the sea and rivers, and return only on the instructions of the authorities. For seriously injured people, gas leaks or fires, call 112; otherwise send a text message instead of phoning, switch on the radio and follow the announcements.
The emergency kit
For the first hours or days after an earthquake, ANEPC recommends an emergency kit, ideally in a rucksack and accessible to everyone in the household. It should contain first-aid supplies, your usual medication, water and long-life food, toiletries, a change of clothes, a radio, a torch and a whistle, a power bank for your phone and the contact details of family and friends. Check it regularly and replace supplies that have expired.
In the same leaflet, ANEPC reminds readers that after a major earthquake the state first restores roads, energy, communications, airports, schools and hospitals and cannot help everyone at the same time. It expressly makes protecting your own property and assets the responsibility of each individual.
After the earthquake: reporting the damage
You report earthquake damage to the insurer within the deadline in your contract, and if it sets none, within 8 days of the day you become aware of it (Artigo 100.º, Decreto-Lei n.º 72/2008). After a large earthquake many people report at the same time, and loss adjusters are scarce. If you report your damage early, in full and with photos, you avoid queries that delay processing.
What to document
- Photos and videos of all cracks and of damage to the roof, chimney and walls, from outside and inside, with the date.
- The time of the earthquake and of any aftershocks you noticed, because this determines whether there is one claim or several.
- Honestly separate damage that existed before the earthquake: earlier damage is excluded in both sets of terms.
- Emergency measures such as propping up or covering, backed by an invoice, but do not demolish anything before the loss adjuster has visited, unless there is danger.
How a claim is reported in Portugal and what loss adjusters expect is shown in our article with tips for a smooth claims process.
After an earthquake, the first impulse is to clear up broken glass and plaster over cracks. A crack that has disappeared before the loss adjuster’s visit can hardly be attributed to the earthquake afterwards. Secure whatever prevents further damage and document everything else first.
Portugal versus what owners sometimes assume
It is easy to assume that earthquake is automatically part of a home policy. In Portugal, in the two sets of terms evaluated, it is a separate module, and a fire after the earthquake is excluded from the fire cover. How high the excess is and how aftershocks are grouped is set by the terms of the individual insurer.
What owners sometimes assume
Earthquake comes with the home policy
- Earthquake is covered automatically with the home insurance
- A fire caused by an earthquake is paid for by the fire cover
- Most homes are insured against natural hazards, including earthquakes
What actually applies in Portugal
A module of its own
- Earthquake with Fidelidade and Generali only as a module of its own (Fenómenos Sísmicos), if agreed in the condições particulares
- Fire caused by an earthquake excluded there from the fire cover
- Only 19 to 20 per cent of dwellings had earthquake cover at the end of 2022 (ASF)
The Portuguese side is based on the two sets of policy terms and the ASF analysis. Whether a policy from another country covers your house in Portugal at all depends on the contract; check this with your insurer. How house insurance in Portugal is structured is explained on our page on the subject.
Earthquakes in Portugal: six mistakes that get expensive
Six mistakes make earthquake damage in Portugal needlessly expensive for owners, from the missing module to the cracks plastered over before the loss adjuster’s visit.
Frequently asked questions
Answers to common questions from owners abroad about earthquakes and home insurance in Portugal.
Does Portugal have earthquakes?
Yes, Portugal is an earthquake region. The last major quake on the mainland occurred on 28 February 1969 in the Atlantic off the south-west coast of Portugal, with a moment magnitude of 8.0, felt most strongly in the Algarve. A more recent example is the quake of 26 August 2024 with a magnitude of 5.3 off Sines, which caused no major damage.
Is earthquake insurance compulsory in Portugal?
No, not today. The only legal requirement is fire insurance for buildings in a condomínio under Artigo 1429.º Código Civil. On 28 April 2026 the government announced a catastrophe fund and compulsory insurance for residential buildings; as far as we could establish, no law on this had been published by October 2026.
Does my home insurance pay for an earthquake?
With Fidelidade and Generali only if earthquake cover is agreed in your condições particulares. There it is an add-on module called Fenómenos Sísmicos. If it is not in your policy, the earthquake peril is not covered and a fire after the earthquake is expressly excluded; check your policy if you are with another insurer.
Does fire insurance pay for a fire after an earthquake?
Not under the terms of Fidelidade and Generali. Both exclude a fire caused by an earthquake from the compulsory fire cover. It is insured there only through the earthquake module, which expressly includes the consequential fire.
How high is the excess for earthquake damage?
That is stated in your condições particulares, with Fidelidade and Generali usually as a percentage. Where the insurer’s liability is only partial, Fidelidade provides a percentage share in the loss plus a franquia (deductible); in its earthquake clause Generali describes a share of the loss, while the general rule mentions a possible share of the sum insured. Check what the percentage applies to, because if the basis is the sum insured, the excess is much higher.
Are aftershocks a separate claim?
With Fidelidade and Generali, all damage within 72 hours of the first damage counts as one claim. The excess therefore applies only once. Whether a later aftershock counts as a new claim is not expressly regulated by the clauses; the insurer decides that according to the circumstances.
Can an old house be insured against earthquakes?
That depends on the insurer and on the construction. Fidelidade and Generali exclude buildings that do not consist of at least 50 per cent resistant material, and Generali also excludes buildings of recognised fragility such as timber or plastic sheets. Fidelidade also ties it to the building regulations in force when the building was built. Have the acceptance of your house confirmed in writing.
How do I prepare for an earthquake in Portugal?
The civil protection authority ANEPC advises fixing shelves and heavy furniture to the wall and deciding on a safe place for everyone in the household, such as interior doorways, corners of load-bearing walls or under a sturdy table. Keep an emergency kit with water, long-life food, medication, first-aid supplies, a radio and a torch ready, and show everyone how to turn off electricity, water and gas.
What should I do during an earthquake?
The civil protection authority ANEPC recommends Baixar, Proteger, Aguardar: drop to your knees, protect your head, neck and eyes, and wait until the ground is still. Indoors, do not rush to the exit and never use the lift. After the earthquake, expect aftershocks and possibly a tsunami, and call 112 for seriously injured people, gas leaks or fires.
How quickly must I report earthquake damage?
Within the deadline in your contract, and if it sets none, within 8 days of the day you become aware of it, under Artigo 100.º of the Portuguese Insurance Contract Act. Photograph all damage before you repair or clear up anything.
Our advice as an independent broker
An earthquake is rare in Portugal, but a large one can destroy a house. Check whether the Fenómenos Sísmicos module is agreed, for the building and the contents, how high the excess is and what it applies to, and whether the insurer has accepted your house without restriction. In a condomínio, the question also belongs on the agenda of the owners’ meeting.
As an independent insurance broker, we are not tied to any insurer. We go through the condições particulares of your existing house insurance in Portugal with you, compare earthquake modules and excesses across the market and tell you which gap remains. We advise in English. For our clients, we deal with the Portuguese insurer and the loss adjuster if there is a claim, even if you are abroad at the time.
We check whether your policy includes earthquakes, work through the excess with you and obtain quotes for the building and contents. In English, with no obligation and independent of any insurer.
Phone: +351 289 392 452
C1 Broker, Av. Duarte Pacheco 13 R/C, 8135-104 Almancil, Quinta do Lago
Prefer to write? Use our contact page.
Last updated: 12 October 2026. This guide reflects the information available on that date and does not replace individual advice or legal advice. The information on Fidelidade is based on the Condições Gerais Fidelidade Casa Mais, Mod. MR011, September 2026, where only the Portuguese wording is binding; the information on Generali on the Condições Gerais Multirrisco Casa, Mod. 465.031, July 2025. The two sets of terms are two examples, not a statement about the market; other insurers handle individual points differently. Only the terms of your own policy apply to your contract. The behaviour recommendations reflect the ANEPC leaflet (as of November 2018). The ASF figures refer to the end of 2022. As far as we could establish, no decision on the announced compulsory insurance had been published by the date stated. The worked example is based on assumed amounts.